
You pay for insurance every month. Then you go to the doctor, use your insurance, and somehow still end up with a bill. Throw in confusing terms like deductible, premium, and coinsurance, and we’re all thinking the same thing: What exactly am I paying for?
Instead of wading through the insurance agent jargon, let’s break down the numbers behind the madness. Consider this Health Insurance 101.
The monthly cost of being insured
Your health insurance premium is what you pay to keep coverage active, whether you visit a doctor or not. It’s like your car insurance. You pay for it even if you don’t use it, and when you need it, you’ll be glad you have it.
If your premium is $400, you’ll still pay this every month to keep your policy active. It doesn’t matter if you see a doctor twice, 20 times, or not at all. You’re stuck paying it if you want to be insured.
If you get insurance through your work, your employer may cover part of the premium. If you go with the Marketplace, you might qualify for subsidies that lower your cost. You can also choose individual or family plans with different premiums and coverage options.
Just remember that a lower monthly premium can mean higher costs when you actually need care. The cheapest premium doesn’t necessarily mean you’re getting the cheapest plan.
Meet your deductible
Your health insurance deductible is the amount you pay for certain covered medical services before your insurance starts sharing the cost.
Let’s say you have a $2,000 deductible. That doesn’t mean you’ll pay $2,000 every time you step foot in a doctor’s office. You just pay the insurance network’s special rate (aka the allowed amount) for each service you get. Once you’ve paid $2,000 toward covered services that count toward your deductible, your insurance starts picking up its share.
So, if a service has an allowed amount of $300, you’d pay that amount, and it would go toward your deductible. You’d need to pay $1,700 more before the insurance takes on its share of the load. (And sorry, your premium doesn’t count toward the deductible.)
But there are exceptions to the rule. Certain preventative services, such as immunizations and recommended screenings, are covered even before you’ve met your deductible. Some plans also have separate prescription deductibles, while family plans may have individual and family deductibles.
Once you’ve hit that $2,000, insurance is ready to take over, right? Unfortunately, it’s not that simple.
Get more articles like this straight to your inbox 
Free as a meme, easy to bail anytime.
How the bill gets split
Congratulations! You’ve met your deductible. Your reward is a whole new set of charges. That’s right, your insurance now shares costs. Notice we emphasize “shares” because you’re still not off the hook yet. Allow us to introduce you to copays and coinsurance.
A copay is a fixed fee, like $30 for a doctor’s appointment or $50 for a visit to a specialist. Depending on your plan, you might still have to pay that amount even before you meet your deductible.
Coinsurance is a percentage that you’ll be responsible for paying. If your plan has 20% coinsurance and a covered service costs $200 after you’ve met the deductible, you’ll pay $40. Your insurer pays the rest.
Both represent your share of the bill. One just requires a little extra math.
And remember, if you haven’t met your deductible yet, you’ll usually pay the insurance-negotiated rate for services that count toward it.
There’s a limit to what you pay
At this point, it feels like you’ll never stop getting a bill for healthcare. While this might be true for your insurance premiums, you’ll be glad to know that there’s some relief with the out-of-pocket maximum.
The out-of-pocket maximum is the most you’ll pay during your plan year for covered, in-network medical care. Your deductible, copays, and coinsurance usually count toward that limit.
Say your maximum is $6,000. Once your qualifying payments hit that amount, your insurer covers 100% of covered in-network services for the remainder of the plan year. Now we’re getting somewhere!
But hold off on the confetti cannons because even the limits come with their own limitations. Your monthly premium doesn’t count toward the maximum, and neither do non-covered services. Out-of-network expenses usually don’t count either.
Who you see changes what you pay
You might have the best doctor in the world, but your insurance company only cares about whether they’re in its network.
- In-network providers have contracts with your insurer. As a result, you’ll pay lower costs.
- Out-of-network providers don’t have these same contracts. Depending on your plan, that could mean much higher bills or no coverage at all. There are special rules for emergency services, but don’t assume that every visit gets the same treatment.
And (surprise!) it gets even more complicated. Your doctor’s office may accept your insurance, but that doesn’t mean it accepts your specific plan.
One year, one plan: start to finish
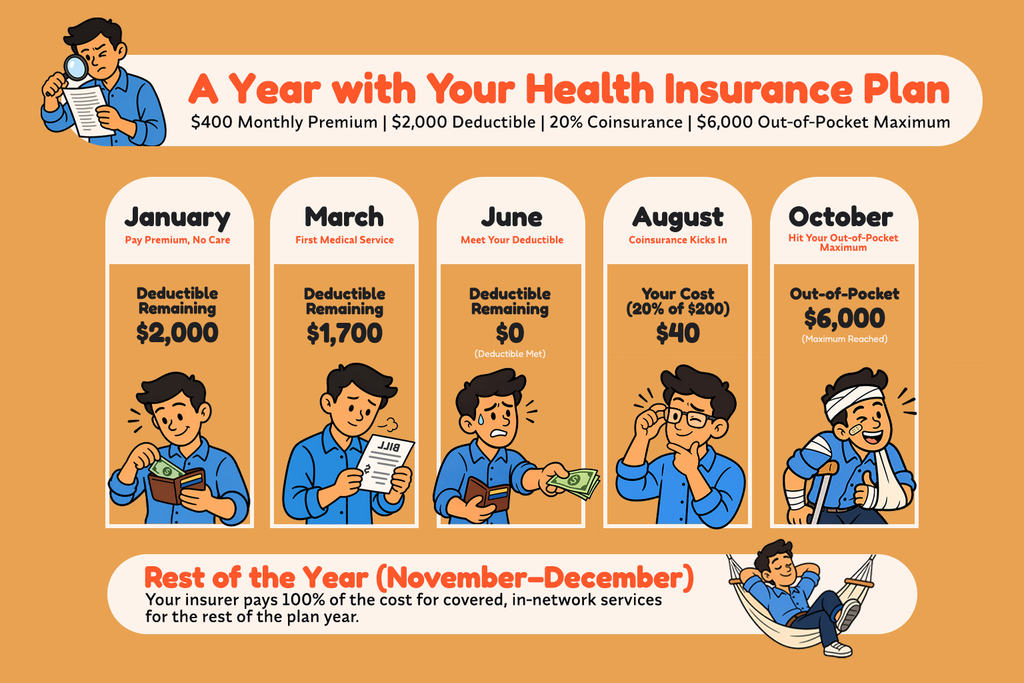
Now, let’s put it all together using a fictional insurance plan with a $400 monthly premium, $2,000 deductible, 20% coinsurance, and a $6,000 out-of-pocket maximum. Here’s what a year would look like:
- January: You pay your $400 premium but don’t need medical care. Your deductible stays at $2,000.
- March: You receive a service with a $300 allowed amount that applies to your deductible. You pay $300, leaving $1,700 of your deductible to meet.
- June: You have additional medical expenses that bring your total deductible payments to $2,000. You’ve met your deductible.
- August: You require a medical service that costs $200. Coinsurance kicks in, so you’ll pay 20% for the covered service – just $40.
- October: By this time, your deductible, copays, and coinsurance have added up to $6,000. Because you hit your maximum, your insurer now pays the full cost of covered in-network services for the rest of the plan year.
Your monthly premiums, unfortunately, didn’t get the memo. So, even in this example, you’ll continue to pay those to keep your coverage active.
The built-in cheat sheet
Still confused? Don’t worry – it’s a lot to take in. The good news is there’s a document that can help you make sense of it all. Think of it as your insurance instruction manual.
Your Summary of Benefits and Coverage (SBC) breaks down your plan’s deductibles, copays, coinsurance, network rules, exclusions, and coverage examples in an easy-to-understand format.
Whether you’re just comparing plans or already insured, reviewing your SBC can help you understand what you’re paying for and what you could owe when you need medical care. Sure, it’s not fun to do homework now, but it’s a lot better than learning about the fine print when it’s attached to a surprised medical bill.